Top-of-wallet is won daily
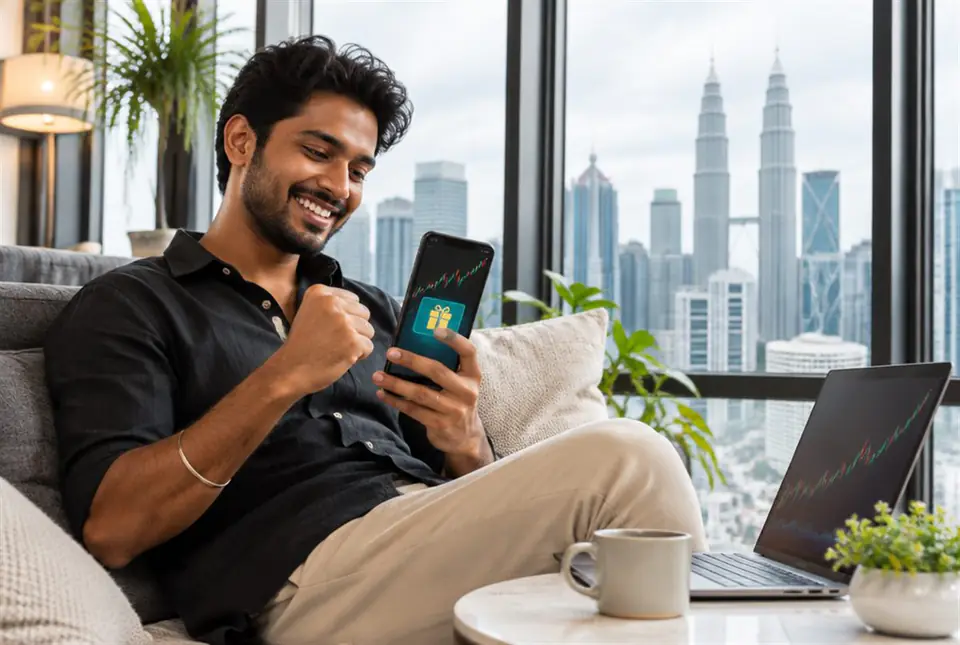
Every tap is a choice between cards. A visible points balance and a voucher within reach tip that choice your way.

Solution
Bank loyalty programPixalink runs the points and voucher engine behind your cards. Post transactions by API, let cardholders see points and redeem digital vouchers inside your banking app, and hand voucher management and distribution to us. Built for banks, digital banks, trading apps and insurers.
 Points per transaction via API
Rewards mini program inside your app
Digital vouchers managed for you

Halia Bank Rewards
RM10 café voucher redeemed for 1,500 points. Show the code at the counter.

Points from card spend
+2,500 pts
Posted by API after settlement
Quick answer
A bank loyalty program rewards customers for using a bank’s cards and products, usually with points for every ringgit spent that can be redeemed for vouchers and perks. Pixalink powers the back end: your card system posts transactions by API, Pixalink issues points and manages digital vouchers, and cardholders see their points and redeem vouchers in a mini program inside your banking app.
Pixalink Sdn Bhd, Malaysia · Updated 8 November 2026

Banking Loyalty at a glance
For
Banks, card issuers, digital banks, trading apps, insurers
Points
Issued per transaction or event via REST API
Vouchers
Digital codes, including third-party code pools, claimed in store
In your app
Branded mini program with single sign-on
Integration
REST API, bulk import, signed webhooks, OpenID Connect
Engagement
Enterprise project scoped in consultation
Credit card rewards in Malaysia
Payments are going digital fast, and cardholders carry more than one card. Rewards are how a bank earns the default spot in the wallet.
Every tap is a choice between cards. A visible points balance and a voucher within reach tip that choice your way.

E-payments and contactless card use in Malaysia grew strongly in 2025, so there are more transactions to reward and more data to personalise.

Surveys of cardholders consistently place rewards among the leading reasons for choosing a card.
e-payment transactions in Malaysia in 2025, up 25%
18.4 billion
Bank Negara Malaysia, Annual Report 2025
contactless payments in 2025, up 20.3%
2 billion
Bank Negara Malaysia, Annual Report 2025
of consumers name rewards as the leading factor when choosing a credit card
58%
Marqeta, 2023 State of Credit (US survey)
Financial services loyalty program
Three engagement models, used alone or together. Each one is scoped with your team in a consultation.
01

Keep your own app and brand. Your card or core system posts transactions to Pixalink by API; Pixalink runs the points ledger, rules, expiry and vouchers, and reports back through signed webhooks.
Best for
Banks and card issuers with an existing rewards front end02

No loyalty solution yet? Open a branded rewards mini program inside your app with single sign-on. Cardholders see their points and redeem vouchers without a second login or a second app.
Best for
Smaller and digital banks, fintech and insurers03

Hand Pixalink the digital voucher catalogue: import code pools, set point prices, distribute vouchers to cardholders by points or campaign, and validate redemptions.
Best for
Teams that want rewards without running a rewards deskHow it connects
Your systems stay the source of truth. Pixalink sits between your card platform and your customers, keeping the points ledger and vouchers, and talking to both through documented APIs.

Core banking & card system
Your systems of record
Settled card transactions
Customer list (bulk import)

API & signed webhooks
Token or OAuth scopes
Issue points per transaction
Events back to your systems
Pixalink points & voucher engine
Ledger, rules, catalogue
Points, tiers, expiry
Voucher code pools, wallet credit

Mini program in your banking app
Single sign-on, your brand
See points and history
Redeem vouchers

Merchant redemption
Digital voucher, claimed in store
Show code or QR at the counter
Validated by API
 Points per transaction API
 Validate & redeem voucher API
 Bulk customer import
 Third-party voucher code pools
 SSO mini program
 Signed outbound webhooks
 Wallet credit
 OpenID Connect sign-in
Orange pulses: transactions and customers flowing in. Blue pulses: signed webhook events flowing back to your systems.
Interactive · points to vouchers
Card spend earns points at the rate you set. Points buy digital vouchers from your catalogue, and the voucher code appears in the cardholder’s app, ready to show in store. Try it.
Banks, fintech and insurers
Four common set-ups. Illustrative brands; every programme is designed with your product and compliance teams.

12,480
pts.
|

0.00
cdts.
Reward Marketplace
My Rewards

Search rewards
RM10
CAFÉ
RM10 Café Voucher

1,500
ptsRM20
GROCERIES
RM20 Grocery Voucher
3,000
ptsRM50
PLATINUM ONLY
Platinum Dining (Platinum only)
6,000
pts2 FOR 1
CINEMA
2 Movie Tickets
6,000
ptsRetail bank · credit card loyalty program
Post settled card transactions to Pixalink and points are issued under your rules. Card tiers can earn at different rates and unlock tier-only vouchers, and expiring points trigger a reminder before they lapse.

Points per transaction: issued by API after settlement.
Tier perks: points multipliers and Platinum-only vouchers.
Breakage control: point expiry with reminders by WhatsApp, email or push.
Book a consultation and we’ll sketch the integration, the catalogue and the responsibilities on each side.

Outsourced voucher management
Yes. Pixalink can run voucher management and distribution as part of an enterprise engagement: importing voucher code pools, pricing them in points, distributing them to cardholders based on points or campaigns, and validating redemptions in store.
Curated catalogue: a digital voucher catalogue sourced with partner merchants as part of the engagement, confirmed in consultation.
Your own partners too: import codes you already buy from third-party providers.
Digital only: vouchers are claimed in store with a code or QR. Pixalink does not ship physical items.
Incentivise usage: release vouchers as cardholders hit points milestones, to encourage card use.
RM10
CAFÉ
 Digital code
RM20
GROCERIES
Digital code
RM15
RIDES
Digital code
RM30
DINING
Digital code
2 FOR 1
CINEMA
Digital code
RM50
WELLNESS
Digital code
 Partner merchants

 Code pools in Pixalink
 Cardholders by points
Clear responsibilities
A typical split. The final scope is agreed in the engagement.
Typical split of responsibilities between Pixalink and the bank

No
Enterprise engagement
Tell us about your cards, app and customers. We’ll come back with an integration outline and next steps.
A programme that rewards customers for using a bank’s cards and products, usually with points per ringgit spent that can be redeemed for vouchers and perks. Pixalink provides the points and voucher engine, an in-app rewards mini program and voucher management.
Your card system posts settled transactions to the Pixalink API, which issues points under your earn rules. Cardholders see their balance and redeem digital vouchers in a mini program inside your banking app, and Pixalink sends signed webhook events back to your systems.
Yes. Add a button in your banking app that opens a branded Pixalink rewards mini program with single sign-on, so cardholders are logged in automatically. You do not need to build a rewards app.
Yes, as an enterprise engagement. Pixalink can import voucher code pools, price them in points, distribute them to cardholders by points or campaign, and validate redemptions. Vouchers are digital and claimed in store; Pixalink does not fulfil physical items.
There is no self-serve cross-brand marketplace. A curated digital voucher catalogue can be sourced with partner merchants as part of an enterprise engagement, and you can also import codes from your own voucher providers. We confirm the catalogue during consultation.
Yes. Any financial service can post events, such as a renewal, a premium payment or a first deposit, through the API and reward customers with points or vouchers. Your compliance team approves the reward rules.
API access uses tokens or OAuth scopes, outbound webhooks are signed so your systems can verify them, and the mini program opens through a short-lived signed SSO link. Pixalink can also act as an OpenID Connect sign-in provider.
Works well with
Loyalty Points
Every ringgit earns a reason to return

Rewards & Vouchers
Vouchers staff can validate in one tap

Credit Wallet
Closed-loop wallet with bonus credit

Mini Program
Scan, join and start in seconds

Membership Tiers
Multipliers, tier-only rewards, invite-only tiers

Loyalty Analytics
Reports that drive daily decisions
Ready when you are
In a consultation we map your card portfolio, integration and voucher catalogue, then propose a pilot.